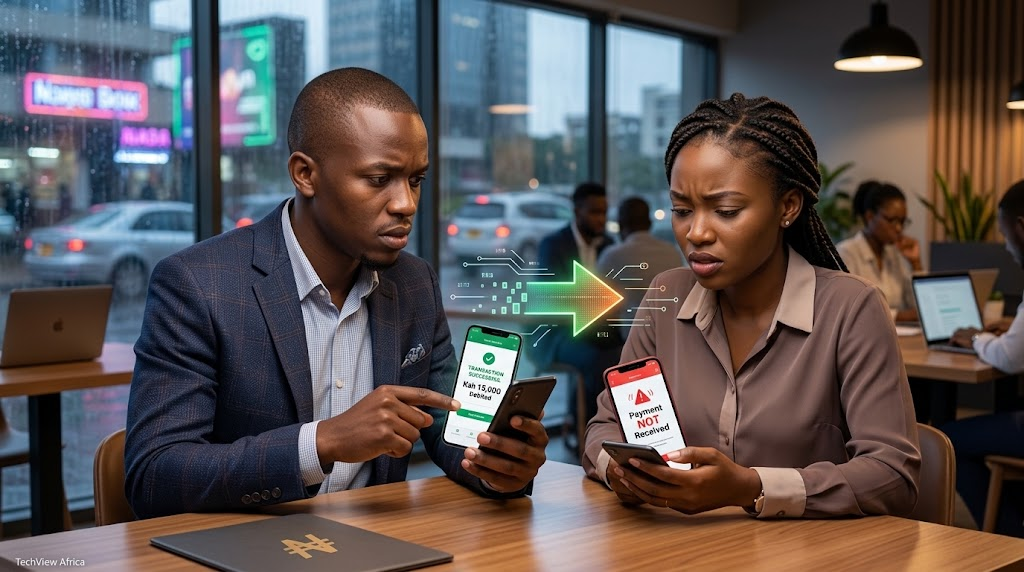
Being debited does not always mean the receiver has been successfully credited. Confirm the original transaction status before paying again, keep your transaction reference and report unresolved transfers through your bank's official support channels.
You send money. Your balance drops immediately. The banking app flashes “Successful.” Then the receiver checks their account and nothing is there. Before sending the money again, find out where the first transfer actually went.
First rule: do not send it again
Imagine transferring ₦75,000.
Your banking app immediately removes the money and displays: Successful.
The receiver checks their account.
Nothing. At this point, many people make the worst possible move: they repeat the transfer.
Don't, not yet.
A debit on your account and a credit on the beneficiary's account are separate parts of an electronic payment. If something goes wrong between them, the sender can appear to have paid while the receiver is still waiting. Fortunately, Nigerian bank customers have more options than simply staring at a receipt and hoping the money appears.
Find out which of three things happened
A “debited but not credited” complaint usually falls into one of three situations.
The transfer may have failed, meaning the sender should expect a reversal.
It may have been successfully processed, but the beneficiary's account has not reflected the credit properly. Or
The transaction may still be unprocessed or incomplete on the sending side.
Those situations can look almost identical inside a banking app. Their solutions are not identical. That is why the sentence “my app says successful” should be the beginning of an investigation not the end of one.
The NIBSS check many Nigerians still do not know about
For eligible NIBSS Instant Payment transactions, the Nigeria Inter-Bank Settlement System provides a transaction-status service. Dial:5655# from the phone number linked to the sender's bank account.
NIBSS says customers can use the service to check eligible NIP transactions completed within the previous 48 hours, including their five most recent NIP transactions. The service currently attracts a ₦20 charge. You provide the sender's account number and the transaction amount, then receive a result.
Verification: NIBSS NIP Transaction Tracker
What the result says matters.
If NIBSS shows “No”
NIBSS says a “No” result means the transfer was unsuccessful. The sender should expect a reversal from their bank. If the reversal does not arrive, the sender should contact the sending institution. That is very different from a situation where the payment successfully reached the receiving side.
If NIBSS shows “Yes”
A “Yes” result means NIBSS records the transfer as successfully processed. If the beneficiary still cannot see the money, NIBSS specifically advises the beneficiary to contact their bank. This distinction can save hours of calling the wrong institution. If the sending side completed successfully, repeatedly asking the sender's bank to “push the money” may not address a posting issue at the beneficiary's bank.
If the transaction is missing
If the transfer does not appear among recent NIP transactions, NIBSS says it may not yet have been processed by the sender's bank. In that case, the sender should contact the sending institution.
No credit alert does not always mean no credit
Before opening a formal dispute, the receiver should check the actual account balance and transaction history.
SMS alerts can arrive late.
Push notifications can fail.
Banking apps can require refreshing.
A network interruption may prevent an alert even though the account has already been credited. So the important question is not:
“Did you receive an alert?”
It is:
“Does the transaction appear in your account?”
That simple distinction can prevent a dispute over money that has already arrived.
How quickly should an NIP transfer be resolved?
Nigeria's instant-payment rules are designed around rapid processing. CBN's instant electronic funds transfer framework includes sanctions where a failed NIP transaction is not reversed within 24 hours and where inward NIP credit to a beneficiary is delayed beyond four minutes.
The framework also recognises that security, system or other issues may sometimes make immediate credit impossible. In such circumstances, the receiving institution is expected to apply the pending credit once the issue is resolved, with the relevant rule providing an outer timeframe of 24 hours.
That does not mean every customer complaint will disappear precisely on the twenty-fourth hour. It does mean there are formal payment-system expectations behind what customers are sometimes casually told is a “network issue.”
Your transaction reference may matter more than your screenshot
A screenshot displaying Successful is useful evidence. A transaction or session reference is even more useful.
When reporting the problem, preserve:
- The exact transfer amount
- Date and approximate time
- Sender's and beneficiary's banks
- Beneficiary's name and account number
- Transaction/session reference
- Transfer receipt or screenshot
- NIBSS status, where available
Then ask the financial institution for a complaint reference number. CBN's Consumer Protection Regulations require financial institutions to generate a unique identification number for complaints and acknowledge them within 24 hours.
That reference converts:
“I called customer service last Tuesday.”
into:
“Complaint reference ABC123 was lodged on Tuesday.”
The second version is much easier to trace and escalate.
Verification: CBN Consumer Protection Regulations
Which bank should you contact?
Use the transaction status to guide you. If the payment failed, the sender should follow up with the sending bank about reversal. If NIBSS records the transaction as successful but the beneficiary remains uncredited, the beneficiary should raise the issue with the receiving institution. If the transaction appears not to have been processed, the sender should contact the sending bank. The banks may eventually need to resolve the issue through their payment-dispute processes, but beginning with the correct institution can reduce unnecessary back-and-forth.
Do not let urgency make you pay twice
This is especially important when paying a merchant, landlord, school, friend or online seller. The receiver says:
“Nothing has entered. Send it again; the first one will reverse.”
They may genuinely believe that. But the first transfer may still settle. If you send another ₦75,000 before establishing what happened, you could eventually discover that both transfers succeeded. You now have a ₦150,000 problem instead of a ₦75,000 delay. For a high value transaction, trace the first payment before repeating it unless you are comfortable taking the risk of duplicate payment.
Sent it to the wrong account? That is different
A failed transfer and a successful transfer to the wrong beneficiary are not the same problem. If you entered an incorrect account number and the money successfully reached another customer, report it to your bank immediately as an erroneous transfer.
Do not simply say:
“My transaction failed.”
It may not have failed at all.
Recovery can be more complicated because the funds may have reached a valid account successfully. The sooner your bank receives the correct information and transaction reference, the better.
Give customer service something it can investigate
Instead of saying:
“My transfer is hanging.”
Try:
“My account was debited ₦75,000 at 10:42 a.m. on 21 August. The transfer was sent to beneficiary bank/account. The beneficiary says the account has not been credited. The transaction reference is [reference] and the NIBSS status shows [status]. Please investigate and provide my complaint reference number.”
Never include your PIN, password or OTP. A legitimate bank does not need those credentials to investigate a transfer.
When should you escalate beyond the bank?
CBN requires consumers to complain to their financial institution first. Its Consumer Complaints Management System tells customers to obtain a complaint reference from the bank and says the institution should upload the complaint to CBN's system within 24 hours.
CBN's general complaint guidance says unresolved complaints can be escalated to its Consumer Protection Department after the applicable resolution period; its general guidance refers to two weeks for many banking complaints, although some categories have different timelines.
Verification: CBN Consumer Complaints Management System
So give the bank the first opportunity to fix the problem—but do not allow the complaint to disappear into endless phone calls without a tracking number.
What this means
Being debited while the receiver remains uncredited is frustrating, but it does not automatically mean the money has disappeared. Your first job is to determine where the transaction sits. For recent eligible NIP transfers, 5655# can help distinguish between an unsuccessful transfer, a successful payment and one that may not yet have been processed. Then act on the result.
Failed? Follow up for reversal.
Successful but not credited? The beneficiary contacts the receiving bank.
Not processed? The sender contacts the sending bank.
And whatever you do, do not send the money again simply because somebody says:
“It didn't enter.”
A delayed payment can become a duplicate payment remarkably quickly. In a bank transfer dispute, your strongest tools are not frustration and screenshots. They are the transaction reference, the NIBSS status and the complaint number.
Use official channels to verify this information. Never share a password, OTP, PIN or full card details with someone who contacts you unexpectedly.
Sources & Verification
NIBSS — NIP Transaction Tracker
CBN — Consumer Protection Regulations
Frequently asked questions
How do I check whether my NIP transfer was actually successful?
Dial *565*5# using the phone number registered with the sender's bank account. NIBSS says the service can check eligible transactions completed within the last 48 hours and currently costs ₦20.
What does “Yes” mean on the NIBSS tracker?
NIBSS says “Yes” means the NIP transfer was successfully processed. If the beneficiary's account has not been credited, the beneficiary should contact their bank.
What does “No” mean?
It means NIBSS records the transaction as unsuccessful. The sender should expect a reversal and contact their bank if it does not arrive.
Can the receiver get the money without receiving an SMS alert?
Yes. An SMS or push notification can be delayed even when the account itself has been credited. Check the beneficiary's balance and transaction history.
Should I send the transfer again?
Not until you understand the status of the first payment, unless you are prepared for the possibility that both transfers eventually succeed.
Must a failed NIP transfer reverse within 24 hours?
CBN's instant-transfer rules provide for sanctions where failed NIP transactions are not reversed within 24 hours. If yours remains unresolved, lodge a formal complaint with the bank and obtain a complaint reference.
How quickly must my bank acknowledge my complaint?
CBN's Consumer Protection Regulations require financial institutions to generate a unique complaint identification number and acknowledge a complaint within 24 hours.
When can I complain to CBN?
You should first lodge the matter with your financial institution. CBN's general guidance allows unresolved complaints to be escalated after the applicable resolution period, which is generally described as two weeks for many complaints but can vary by category.
Inside the $213 Billion Payments Business Airtel Wants to Take Public
Sent Money to the Wrong Account in Nigeria? Act Fast, Here’s What to Do
Fake Bank Alert or Real Payment: Here’s How to Verify It Properly
Why Nigerians Are Using Stablecoins for Cross-Border Payments and What the Risks Are
Africa Is Connecting Payment Systems: What That Could Eventually Change for Consumers
CBN’s January 2027 Data Rule: What Nigeria’s Banks and Fintechs Actually Have to Move
How to Check Whether an Online Store Is Genuine Before Sending Money
Follow TechView Africa on WhatsApp
Get TechView Africa updates on WhatsApp. Follow our channel for practical technology news, product guides and digital trends from Nigeria and across Africa.
Leave a comment
Comments cannot be edited or deleted after posting. Please review your comment before submitting.
No comments yet. Start the conversation.